Patience Before Planning
Financial preparation for widows.
- CategoryAdvertorials
- Photographed byFabien & Laura Castro
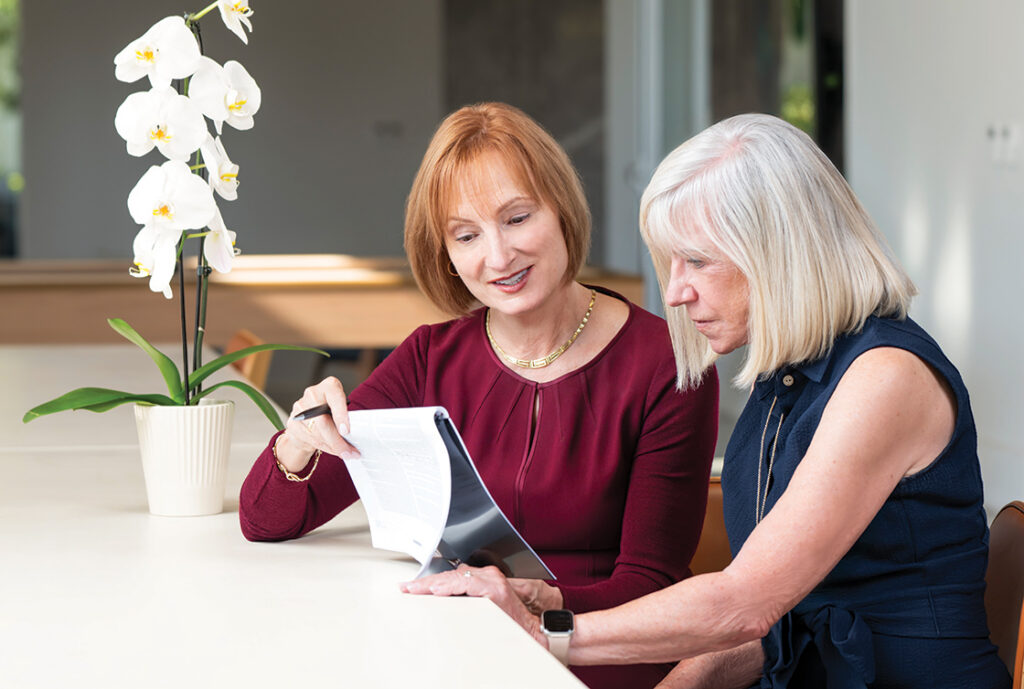 Losing a spouse, whether suddenly or inevitably over weeks or months, is a profound shock. Taking care of one’s basic needs becomes a challenge. While some decisions must be made immediately, financial decisions should not be one of them.
Grief can affect cognitive functioning. Many widows experience brain fog, and their normal decision-making capacity is impaired. Consider postponing major decisions for 12 months, maybe longer depending on the individual. Impulsive decisions made in the moment will be harder to unwind and may affect a widow’s emotional or financial well-being.
When advising a newly widowed woman, a financial advisor should proceed with patience and empathy first, financial planning second. This may sound obvious, but most advisors are motivated to help by finding solutions. Well-meaning financial professionals may rush in to help their widowed client move forward when the client is not ready to do so.
In many situations, a widow has been a part of the financial planning process with her husband, so she is well-equipped to make sound financial decisions as her grief subsides. In other situations, a widow may welcome the help of an experienced financial planner to guide her through financial decisions—short-term and long-term.
The timeliest financial concern is making sure that there is sufficient cash to meet a widow’s living expenses and pay her or the family’s bills. Having enough emergency cash on hand is a vital component of a well-designed and thoughtful financial plan. A cushion of three to six months of living expenses is recommended, depending on each family’s specific situation.
At the death of her husband, a widow should contact the Social Security Administration promptly. A widow can receive between 71.5% and 100% of her deceased husband’s Social Security benefit depending on her age when she files for Social Security and whether she is caring for dependent children.*
Shortly after the death of her husband, a widow should review and update her beneficiaries that are listed on her retirement accounts (401(k), IRA, etc.) and on her insurance or annuity policies. She should also meet with her estate planning attorney to determine if her trust needs to be updated or if any action needs to be taken considering her husband’s passing.
A widow should meet with a financial advisor to carefully review her accounts and decide if any changes need to be made to best serve her going forward. She should not be timid about asking questions; there are no “dumb” questions. If she has a need for income from her investments, determining how much after-tax income she can sustain for herself and her family will be essential.
An experienced financial planner can help guide a widow to a brighter tomorrow with advice, education, analysis and patience.
*Source: ssa.gov/blog/en/posts/2026-0
Disclaimer: Neither RBC Wealth Management, a division of RBC Capital Markets, LLC, nor its affiliates or employees provide legal, accounting or tax advice. All legal, accounting or tax decisions regarding your accounts and any transactions or investments entered into in relation to such accounts should be made in consultation with your independent advisors. No information, including but not limited to written materials, provided by RBC WM or its affiliates or employees should be construed as legal, accounting or tax advice. Investment and insurance products offered through RBC Wealth Management are not insured by the FDIC or any other federal government agency, are not deposits or other obligations of, or guaranteed by, a bank or any bank affiliates, and are subject to investment risks, including possible loss of principal amount invested. RBC Wealth Management, a division of RBC Capital Markets, LLC, registered investment adviser and Member NYSE/FINRA/SIPC.
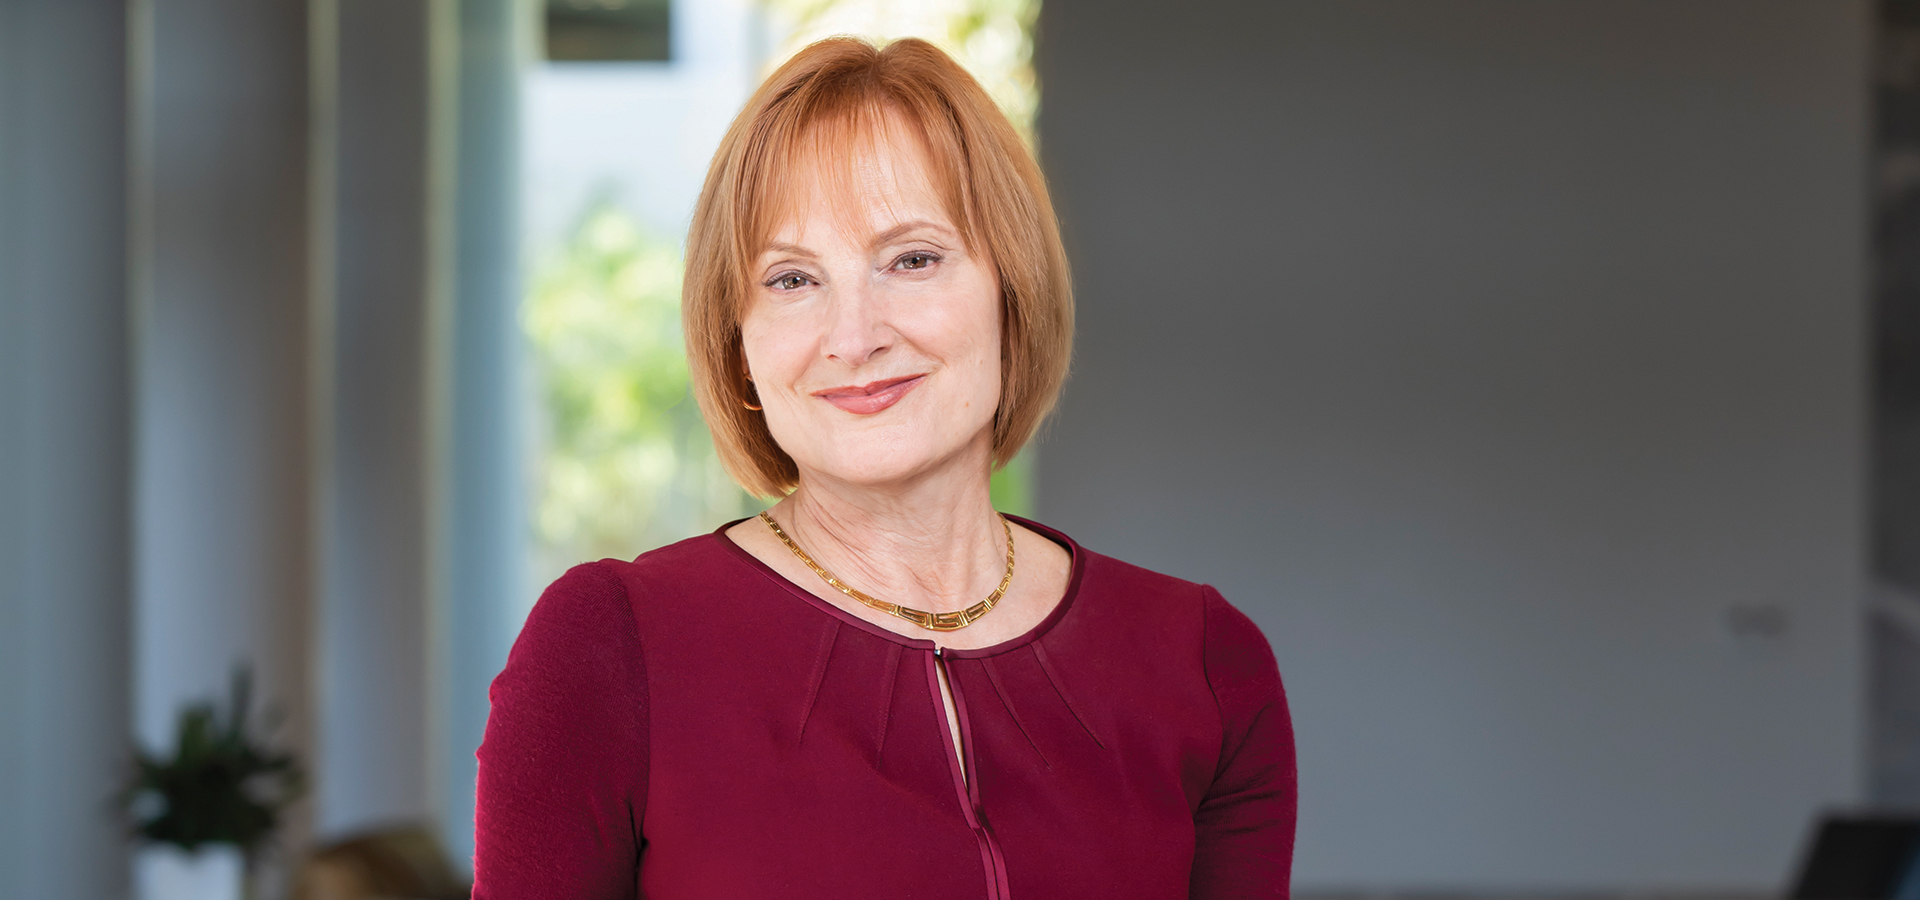
Carol Wilshire is a Certified Financial Planner™ and managing director at RBC Wealth Management based in Manhattan Beach. She has more than 25 years of experience working with widowed and divorced women.
carol.wilshire@rbc.com
310-341-6663
us.rbcwealthmanagement.com/carol.wilshire


Good Times
Manhattan Village flourishes as an exciting destination for lingering, exploring and connecting.